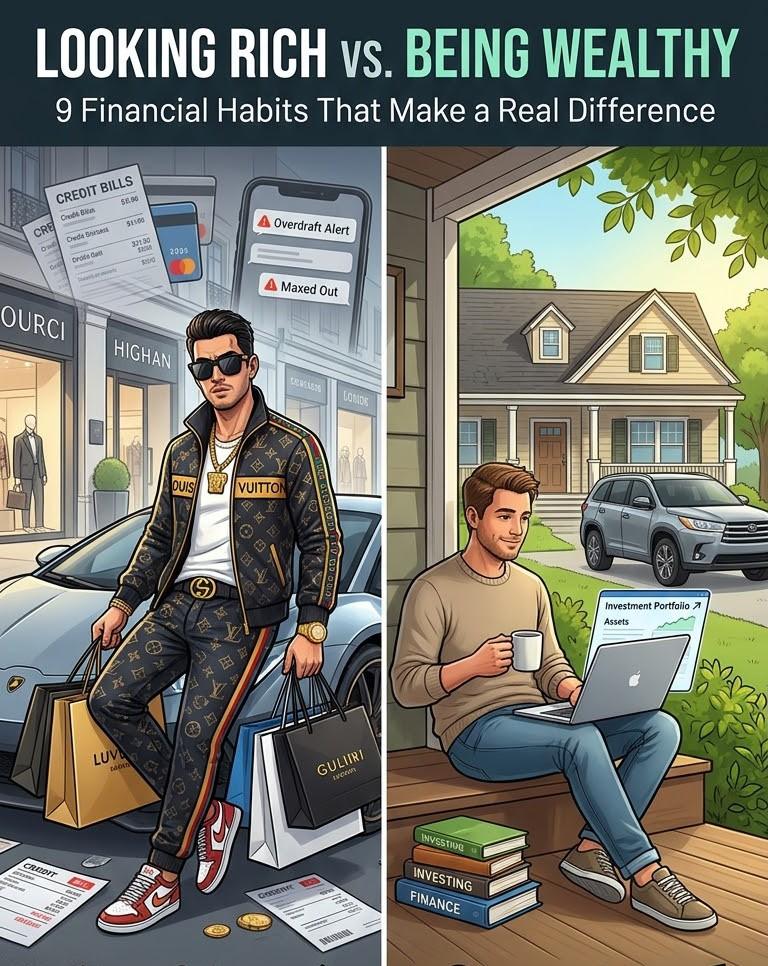
In today's world, it is easy to associate success with expensive clothes, luxury cars, designer accessories, and beautiful houses. Social media has made it even easier to compare our financial lives with those of other people.
Someone who regularly displays expensive purchases may appear wealthy. Meanwhile, someone who dresses simply and lives quietly may have substantial savings, valuable investments, or a business that generates steady income.
The truth is that looking wealthy and building financial security are two different things.
A person can earn a good income and still struggle financially because of excessive spending. Another person with a modest income may gradually build stability through careful planning, consistent saving, and thoughtful decisions.
Your income matters, but how you manage the money available to you also plays an important role.
Here are nine financial habits that can help you focus less on appearances and more on building a secure future.
1. Understand the Difference Between Income and Wealth
Income is the money you receive from activities such as employment, business, freelancing, or investments.
Wealth is different. It generally refers to the value of the assets you own after subtracting what you owe.
For example, imagine two people.
The first person earns a high monthly salary but spends nearly all of it on rent, entertainment, expensive purchases, and loan repayments.
The second person earns less but gradually builds savings, owns useful assets, and avoids unnecessary debt.
Although the first person earns more, the second may be in a stronger financial position.
This does not mean spending money on enjoyable things is automatically wrong. It means that a high income alone does not guarantee financial security.
Instead of focusing only on how much money you earn, consider how much you can retain, what assets you are building, and whether your financial position is improving over time.
2. Stop Spending Money to Impress Other People
One of the most expensive financial habits is buying things mainly to gain approval.
You might purchase a new phone because your friends have newer models. You might spend money on clothes you cannot comfortably afford because you want people to see you as successful.
Sometimes, the pressure is not even spoken. Simply seeing other people display expensive possessions can make ordinary things feel inadequate.
The problem arises when your spending reflects other people's expectations rather than your actual needs and priorities.
Before making a significant purchase, ask yourself:
- Do I genuinely need this item?
- Can I afford it without neglecting important expenses?
- Am I buying it because I value it or because I want to impress someone?
- Will this purchase create financial pressure later?
You do not need to reject every luxury. If you can comfortably afford something you enjoy, buying it may be reasonable.
The goal is to make deliberate decisions rather than allowing social pressure to control your finances.
3. Know Where Your Money Goes
Many people find it difficult to save because they do not have a clear picture of their spending.
Small purchases can appear insignificant individually, but regular expenses can add up over a month.
Transport, food, subscriptions, impulse purchases, delivery fees, and other everyday costs may consume more money than expected.
A simple way to understand your financial habits is to track your income and expenses for at least 30 days.
You can use a notebook, spreadsheet, or budgeting application.
Record your spending and divide it into categories such as:
- Essential expenses, including food, housing, utilities, and transport.
- Financial commitments, including debt repayments and family responsibilities.
- Savings and future goals.
- Optional spending, including entertainment and non-essential purchases.
At the end of the month, review the information.
You may discover that some expenses are necessary, while others can be reduced without significantly affecting your quality of life.
The purpose is not to feel guilty about every purchase. It is to understand your habits well enough to make better decisions.
4. Build an Emergency Fund Gradually
Unexpected expenses can disrupt even a carefully planned budget.
A medical bill, urgent repair, temporary loss of income, or family emergency may require money you did not plan to spend.
Without savings, you may need to borrow money, sell something important, or postpone another essential expense.
An emergency fund can provide some protection against these situations.
If your income is limited, do not assume that saving is pointless unless you can immediately put aside a large amount.
Start with a manageable target.
You might first aim to save enough to cover one small unexpected expense. Once you reach that target, gradually work towards a larger reserve.
Over time, a useful goal is to build savings that can cover several months of essential expenses, although the right amount depends on your income stability, responsibilities, and circumstances.
Keep emergency money somewhere reasonably accessible and separate from the funds you use for ordinary spending.
If you are struggling to meet basic needs, prioritising food, housing, healthcare, and other necessities is more important than forcing yourself to save an unrealistic amount.
The purpose of an emergency fund is to protect you, not to create another source of financial stress.
5. Be Careful With Debt
Borrowing money is not always a bad financial decision. Some loans may help people manage important expenses or fund carefully evaluated opportunities.
However, debt becomes dangerous when repayment costs exceed what a person can realistically afford.
High-interest borrowing can make ordinary purchases much more expensive. Repeatedly borrowing to cover previous debts can also create a cycle that becomes increasingly difficult to escape.
Before taking a loan, understand the total amount you must repay, the interest and fees involved, the repayment schedule, and the consequences of missing payments.
Do not focus only on whether the lender will approve you. Consider whether repayment will leave you enough money for essential expenses.
If you already have multiple debts, list the balances, interest rates, and minimum payments.
Depending on your circumstances, paying extra towards the highest-interest debt can reduce the amount of interest you pay over time, while maintaining required payments on other debts.
If your income cannot cover basic expenses and debt repayments, you may need to contact lenders to discuss available repayment arrangements or seek qualified financial guidance.
Avoid borrowing simply to maintain an appearance of wealth. Temporary admiration from other people is rarely worth long-term financial pressure.
6. Invest in Skills That Can Improve Your Earning Potential
Saving money is important, but your ability to earn can also influence your long-term financial position.
For people with limited incomes, there may be little money left after paying for basic necessities. In such situations, cutting every small expense may not solve the underlying problem.
Developing a useful skill can sometimes create opportunities to increase your income.
Depending on your interests and local opportunities, you might explore skills such as writing, graphic design, software development, bookkeeping, sales, digital marketing, electrical work, or another practical trade.
The best choice depends on what people are willing to pay for, what you can realistically learn, and the resources available to you.
Before paying for an expensive course, research the field carefully. Look for reputable free learning materials, compare training options, and find out what beginners need to demonstrate before they can secure paid work.
Learning a skill does not guarantee employment or business success. However, combining relevant knowledge with practice, reliability, and an understanding of customers' needs can improve your chances.
Treat skill development as a long-term investment in your capabilities rather than a promise of instant income.
7. Do Not Confuse Every Investment Opportunity With a Good Opportunity
When people want to improve their finances quickly, they may become attracted to opportunities promising unusually high returns.
Some advertisements claim that investors can double their money within a short period, earn guaranteed daily profits, or receive substantial returns without taking meaningful risks.
Such promises deserve serious scrutiny.
Every legitimate investment carries some form of risk, and higher potential returns generally come with greater uncertainty. Anyone who promises extraordinary profits without clearly explaining the risks should be approached with caution.
Before investing, make sure you understand:
- What the investment actually involves.
- How the investment is supposed to generate returns.
- What fees you may have to pay.
- Whether you can lose some or all of your money.
- Whether the provider is appropriately authorised or regulated.
- How you can withdraw your funds.
Research independently rather than relying entirely on testimonials, screenshots of profits, or recommendations from people who may benefit from your participation.
Never invest money you need for food, rent, medical expenses, or other immediate necessities.
You do not have to invest in every opportunity you encounter. Sometimes, protecting your existing money is the wiser decision.
8. Set Financial Goals That Match Your Circumstances
Financial goals give your money a purpose.
Without clear priorities, you may spend whatever is available and postpone important decisions until they become urgent.
Start by identifying what matters most to you.
Perhaps you want to build an emergency fund, pay off a loan, buy equipment for your work, pay for professional training, or save towards a business.
Choose one or two priorities and estimate how much money you need.
Next, consider a realistic timeline based on your income and responsibilities.
For example, if you want to save ₦60,000 over 12 months, you would need to set aside an average of ₦5,000 per month, assuming your circumstances allow it and ignoring any interest earned.
If that target is too difficult, adjust the timeline or amount rather than abandoning the goal completely.
Review your progress regularly and make changes when your circumstances change.
A financial plan should help you manage your resources more effectively. It should not require you to ignore essential needs or pretend that your income is higher than it is.
9. Learn to Appreciate Progress That Other People Cannot See
Some of the most important financial achievements are not visible to anyone else.
Paying off a debt, keeping an emergency fund intact, learning a valuable skill, or consistently avoiding unnecessary borrowing may not attract public attention.
You may not receive compliments for these decisions. In some cases, people may even misunderstand why you are choosing a simpler lifestyle.
That does not make your progress less meaningful.
Financial stability is often built through decisions that seem ordinary at the time.
You may choose to repair something rather than replace it, cook at home more often, postpone an unnecessary purchase, or save towards a goal instead of spending money immediately.
These decisions will not automatically make you wealthy, but they can help you direct more of your resources towards what matters to you.
Measure your progress against your own financial goals rather than the possessions displayed by other people.
You do not need to announce every achievement for it to count.
How to Start Improving Your Finances This Month
If these habits seem overwhelming, begin with a simple plan.
Week 1: Understand your money. Write down your income, essential expenses, debts, and regular spending commitments.
Week 2: Identify one change. Find an expense you can reasonably reduce or a financial problem that needs attention.
Week 3: Choose a priority. Decide whether your immediate focus should be emergency savings, debt management, or developing a skill that may improve your earning potential.
Week 4: Review your progress. Check what worked, what proved difficult, and what you need to adjust next month.
Your results will depend on your income, responsibilities, and circumstances. If you cannot save anything after meeting essential needs, that does not mean you have failed. Your next step may be to explore ways to increase your income, access available support, or manage a financial obligation.
The goal is to make informed decisions with the resources you have today while working towards a stronger financial position.
Final Thoughts
Looking wealthy and being financially secure are not the same thing.
Expensive possessions may be enjoyable, but they cannot tell you everything about someone's financial situation. A person who appears successful may be struggling with debt, while someone who lives quietly may be steadily building savings and assets.
You do not need to compete with anyone else's lifestyle.
Focus on understanding your money, managing debt carefully, developing useful skills, preparing for unexpected expenses, and making thoughtful decisions about investments.
Progress may be gradual, especially when your income is limited. Nevertheless, understanding your financial situation gives you a better foundation for deciding what to do next.
The aim is not simply to appear successful. It is to build a financial life that supports your needs, priorities, and future plans.
What Do You Think?
Which financial habit do you think makes the biggest difference: saving consistently, avoiding unnecessary debt, learning new skills, or controlling spending?
Share your thoughts in the comments. Your experience may offer useful ideas to someone working towards better financial stability.

Leave a comment
Your email address will not be published. Required fields are marked *